


Manufacturing production is improving, manufacturing employment is not
- 10.23.26
- Economy & Policy
- Commentary
Raymond James Chief Economist Eugenio J. Alemán discusses current economic conditions.
Manufacturing production began to recover in early 2026 after nearly three years in recession. Yet manufacturing employment has remained largely unchanged. In other words, a year and a half after tariffs were imposed with the goal of boosting manufacturing jobs, that objective remains elusive. What is often overlooked is that higher production does not necessarily require more workers. Improvements in efficiency and productivity, particularly in the most advanced manufacturing industries, frequently allow firms to increase output with the same number of workers or, in many cases, fewer workers.
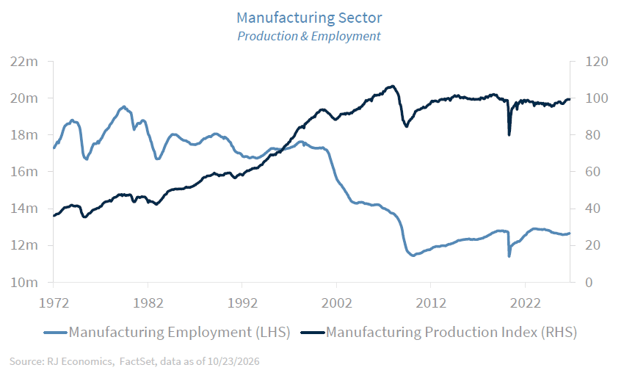
Today, manufacturing production is more than 60% higher than it was in the 1970s, while employment remains 6.8 million below its August 1979 peak. The implication is clear: Manufacturing productivity has increased dramatically, even though total manufacturing output has been relatively flat since the recovery from the Great Recession.
The recent recovery in US manufacturing has been led by durable goods production. However, gains have not been evenly distributed across industries. Only a handful of sectors are producing more today than they did before the Great Recession, most notably computer and electronic products and transportation equipment. Yet neither sector employs more workers today than before the recession.
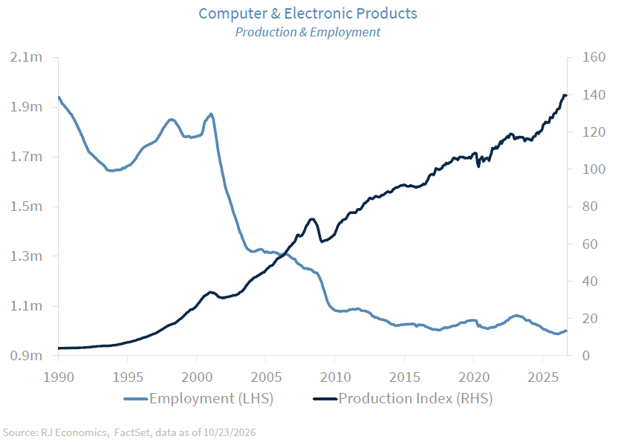
The computer and electronic products sector deserves special attention given the ongoing expansion in artificial intelligence and data center investment. As the chart below illustrates, the sector's output has grown exponentially, making it one of the clearest examples of how productivity gains can transform an industry. Employment has fallen from roughly 2 million workers in 1990 to about 1 million today, yet output has increased by approximately 3,400% over the same period. Within the sector, production of computer and peripheral equipment has risen more than 6,000%, while semiconductor and other electronic component production has surged by more than 70,000%.
Transportation equipment manufacturing is the other major durable goods industry producing more today than before the Great Recession. While employment has declined from a peak of roughly 2.2 million workers in the early 1990s to about 1.8 million today, output has increased by approximately 85% since January 1990.
On the nondurable goods side, production growth has slowed considerably since the Great Recession but has remained relatively stable in recent years. Employment, however, has continued to weaken despite steady output. Among nondurable goods industries, food manufacturing stands out as the only sector employing more workers today than it did in the early 1990s. Although output remains slightly below its post-pandemic peak, employment remains one of the few bright spots in manufacturing. The industry employs approximately 1.8 million workers today, compared with about 1.5 million in January 1990.
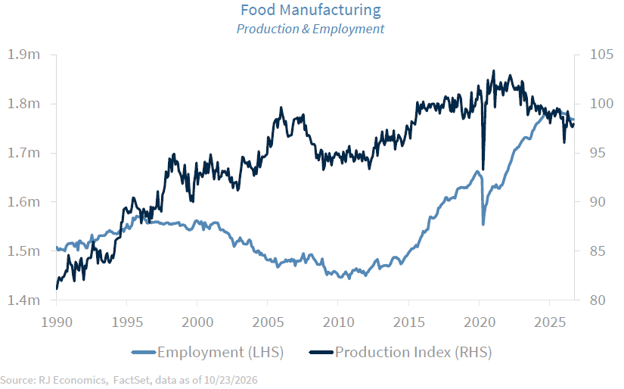
Food manufacturing highlights an important distinction. Unlike many manufacturing industries, production in this sector remains labor-intensive and is less susceptible to substituting capital for labor. By contrast, many durable goods industries, including nonmetallic minerals, primary metals, fabricated metals, machinery and electrical equipment, have increased production without meaningfully expanding payrolls.
Bottom line
Manufacturing employment is significantly lower today than it was in the 1990s. However, productivity has surged across much of the sector. At the same time, some industries have become less competitive relative to foreign producers, particularly those in China. The United States continues to maintain a competitive advantage in technologically sophisticated industries and domestically oriented sectors such as food manufacturing, where labor remains a critical component of production.
Competing against countries with substantially lower labor costs remains challenging. A manufacturing worker in China earns roughly $15,000 per year, compared with approximately $77,000 for a manufacturing worker in the United States before benefits. No realistic tariff can fully offset such a wage gap across all industries. A tariff high enough to do so would effectively become prohibitive, pushing the economy toward autarky, a system in which trade largely ceases and domestic consumption is limited to domestic production. Such an outcome would result in a significant decline in economic welfare.
LHS/RHS: Left-hand side/Right-hand side axes
Economic and market conditions are subject to change.
Opinions are those of Investment Strategy and not necessarily those of Raymond James and are subject to change without notice. The information has been obtained from sources considered to be reliable, but we do not guarantee that the foregoing material is accurate or complete. There is no assurance any of the trends mentioned will continue or forecasts will occur. Past performance may not be indicative of future results.
